Why focus on rARQT right now? What’s the market narrative?
Arcutis Biotherapeutics (
NASDAQ: ARQT, Bitget rARQT) is a commercial-stage dermatology biopharmaceutical company. Its core product is ZORYVE (roflumilast) topical cream/foam for plaque psoriasis, atopic dermatitis, and seborrheic dermatitis — a non-steroidal, once-daily treatment suitable for long-term use.
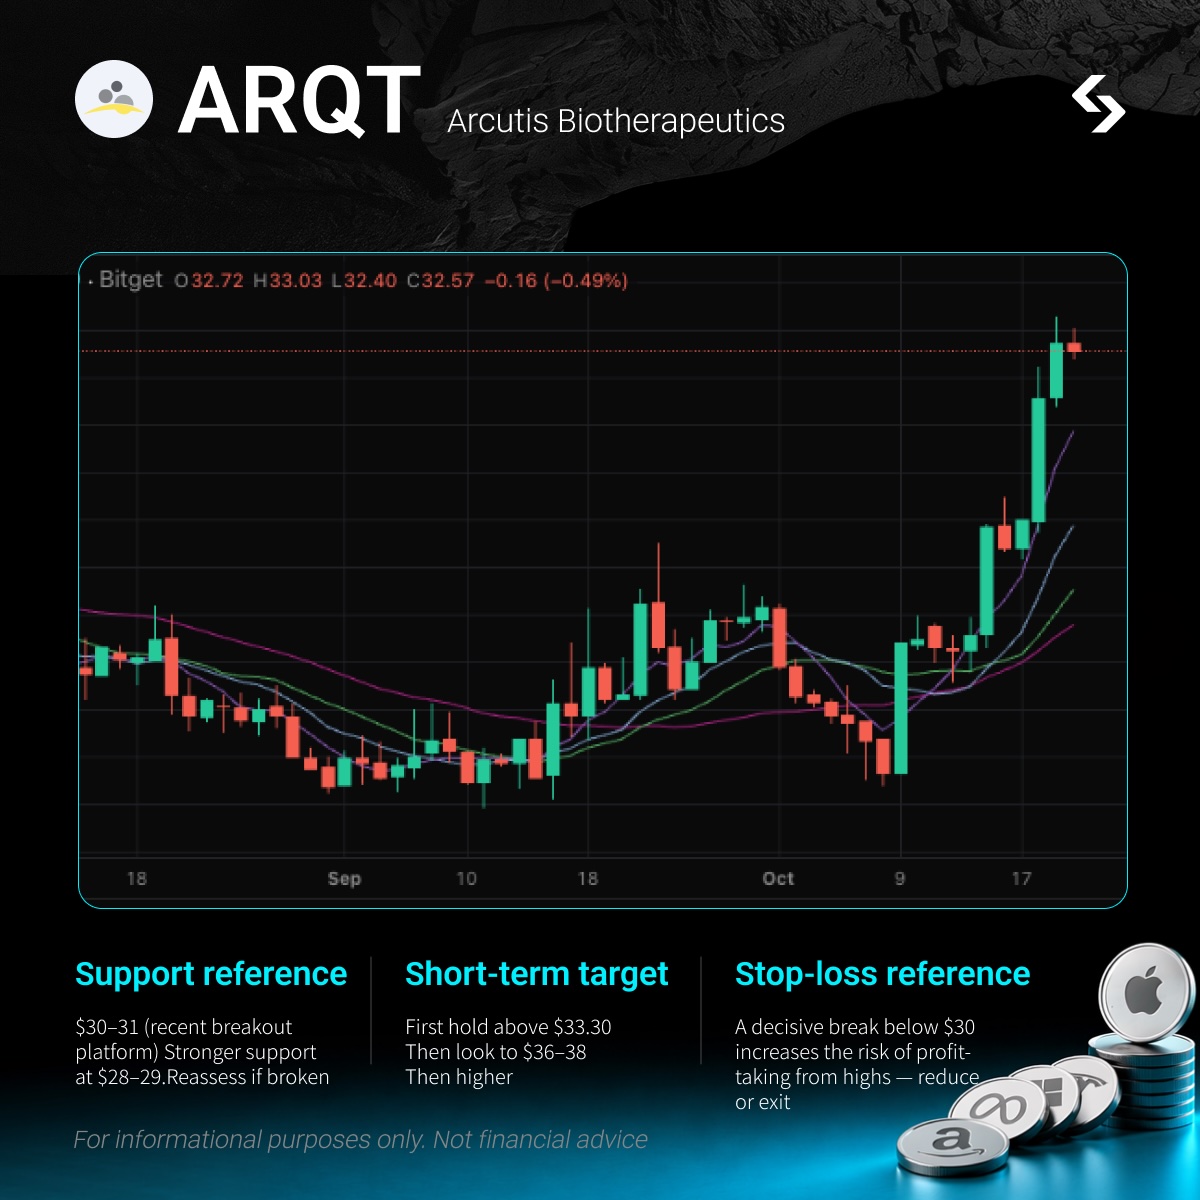
From the May 52-week low of about $19.30, the current price is around $32.82 (October 20 close), up roughly +70%. Recent performance has been strong: it has touched and is now close to the 52-week high of about $33.30 (roughly -1.4% from the high). It is up about +26% over the past week and about +29% over the past month. The market story has shifted from an early clinical narrative to one of proven commercial ramp for ZORYVE, ongoing label expansions (pediatric/infant), sales force and telehealth channel expansion, and the company’s transition into profitability and improving cash flow, with full-year guidance raised multiple times. High volatility + innovative dermatology therapy theme makes it suitable for event-driven swings.
To be clear: short interest is about 21.69 million shares, roughly 18.4% of float (about 17.3% of outstanding shares), with days to cover around 4.8. This is thicker than a pure institutional name but far from a
GME-style extreme squeeze. Trade it as thematic elasticity plus earnings catalysts — not as a blind short-squeeze breakout. The stock is already near new highs.
Fundamentals Snapshot
U.S. dermatology biopharma company headquartered in Westlake Village, California. Core is the ZORYVE franchise (multiple cream strengths + foam) covering psoriasis, atopic dermatitis, seborrheic dermatitis, and other immune-mediated skin diseases, emphasizing non-steroidal alternatives and patient adherence. Commercial efforts have expanded from specialty dermatology into pediatrics/primary care, with prescription volume repeatedly hitting new highs.
Core products and progress:
-
ZORYVE cream/foam: Multiple FDA approvals covering adult and pediatric indications; recently expanded to plaque psoriasis in children as young as 2; infant atopic dermatitis
sNDA accepted (PDUFA target date February 23, 2027).
-
Sales force expansion, telehealth, and patient access programs underway.
-
Pipeline: ZORYVE foam in Phase 2 for vitiligo and others; systemic candidate ARQ-234 in development.
Key financial and operating data:
Market cap ~$4.1B; current price ~$32.82; 52-week range $19.30–$33.30, about -1.4% from the high.
Q2 2026 (ended June 30):
Net product revenue $129.9 million, +59% YoY and +23% QoQ; full-year 2026 net product sales guidance raised to $525–$540 million (from prior $480–$495 million).
Q2 net income ~$15 million; positive operating cash flow; cash and equivalents ~$239 million.
Short interest ~21.69 million shares, ~18.4% of float, days to cover ~4.8; institutional ownership ~89%. Elasticity comes from the theme, prescription ramp, and guidance raises; shorts provide some additional fuel but are not the core driver.
Recent Catalysts
-
August: Q2 beat and significant full-year revenue guidance raise.
-
Mid-to-late October: Cantor initiated Overweight with $48 price target; Guggenheim raised target to $44 while maintaining Buy — driving volume and new 52-week highs.
-
Next earnings window around November 3 (Q3) to verify prescription/revenue continuity, margins, and guidance.
-
Medium-term: Infant indication PDUFA (Feb 23, 2027), Phase 2 data, and continued channel expansion.
Common market view: The stock has already rebounded sharply and is near 52-week highs. Wall Street targets mostly sit in the $38–$44 range, with some of the ramp and raises already priced in. Valuation looks elevated for a growth biotech (forward PE not cheap), and single-product dependency plus competition risks remain. What may be different: Q2 already demonstrated strong demand-driven growth with consecutive raises. The impact of sales force and channel investments should show up in subsequent quarters. If ZORYVE continues taking share from topical steroids and new indications land, some sell-side peak sales outlooks are in the ~$2.6–$3.5B range, leaving room for medium-term re-rating. This is a medium-term expectation gap; near-term moves are more about earnings and analyst sentiment than a pure squeeze.
Key Trading Levels
Logic is clear: ZORYVE volume ramp + guidance raises + label expansions + improving profitability. Mid-sized float and meaningful volatility suit event-driven swings — not chasing blindly above $33. Support reference: $30–$31 (recent breakout zone); stronger support around $28–$29 and the 50-day moving average near $25.6. Near-term targets: First hold above $33.30, then look toward $36–$38 (sell-side target midpoint); if earnings stay strong, $40–$44 becomes discussable. Medium-term upside beyond that only if channel and new indications continue to validate and the sector holds — not a number to hard-code as a target right now. Stop reference: A clean break below $30 raises risk of failed breakout; losing the $28 area means this impulse needs re-evaluation. Note: Already near new highs — size as an elasticity position, not a core holding, and avoid heavy overlap with other high-volatility biotech or previously featured names.
Bitget Convenience
rARQT trades 24/7. Via Bitget rToken rARQT you can position anytime (no need to wait for U.S. market open — capture after-hours and overnight moves), with transparent pricing and automatic tracking without constant monitoring.
Risk Warning
The biggest risks are high-level profit-taking and event outcomes falling short. The stock is already near its 52-week high, so consensus target cushion is limited. If Q3 shows slower prescription growth, guidance miss, or emerging competition/pricing pressure, pullbacks can be swift. Single-product biotech characteristics remain, and clinical/regulatory timing is uncertain. Short interest has some thickness, but the holder base is primarily institutional — after emotional impulses, volume can dry up and prices retrace. High-volatility name; position sizing and stop discipline are critical.
Data and levels are for reference only and do not constitute investment advice. Trade at your own risk.

 2026/10/22 06:47
 VIPWeekly Strategy Tesla