
AI, the Fed, and Inventory Divergence: The Logic Behind Gold Price Rebound

FX168 Finance, October 2—— AI has spurred localized inflation and inventory structure divergence, causing the Federal Reserve’s policy to fall into a dilemma. The decline in real interest rates is driving a rebound in gold prices, with a key focus on nonfarm data for confirmation of future direction.
Recently, gold prices have experienced a rebound, mainly driven by frequent comments from Federal Reserve officials. The market has repriced the probability of a rate hike in October, with the decline in real interest rates lowering the opportunity cost of holding gold, thereby boosting the price of this non-yielding asset. The main focus of the current Federal Reserve discussions centers on the structural inflation driven by AI capital expenditure, which has become a main thread of macro-level gaming.
The Federal Reserve intensively discusses AI’s macro impact, with cooling expectations for an October rate hike boosting gold prices
Several Federal Reserve officials have recently focused on the complex effects of AI on the macroeconomy and inflation.
Federal Reserve Governor Cook stated that AI investment is creating localized inflationary pressures, and such inflation is unlikely to retreat quickly in the short term; the supply shock caused by AI is more persistent than expected, supply bottleneck risks deserve vigilance, and there is a need for careful assessment of AI’s long-term remolding of the labor market structure, in order to prevent inflation expectations from being unanchored.
Williams also pointed out that the impact of AI on the supply side is not fully understood yet. As AI is implemented in manufacturing, logistics and other sectors, it is reshaping capacity and resource allocation, and its long-term effects require continued observation.
Kashkari, Jefferson, and Logan also discussed economic resilience and inflation stickiness: Kashkari believes the economy and labor market remain strong, and the current monetary policy may not be restrictive enough (i.e. it does not affect the job market), so there is still a need for additional hikes, but he did not express a strong inclination about an October move;
Jefferson advocates needing more time to observe data trends, instead of making decisions based on single-month data; Logan suggested that the rising term premium on US Treasuries can substitute for some rate hikes, but overall, at least another 50 basis points are needed to balance inflation and employment goals.
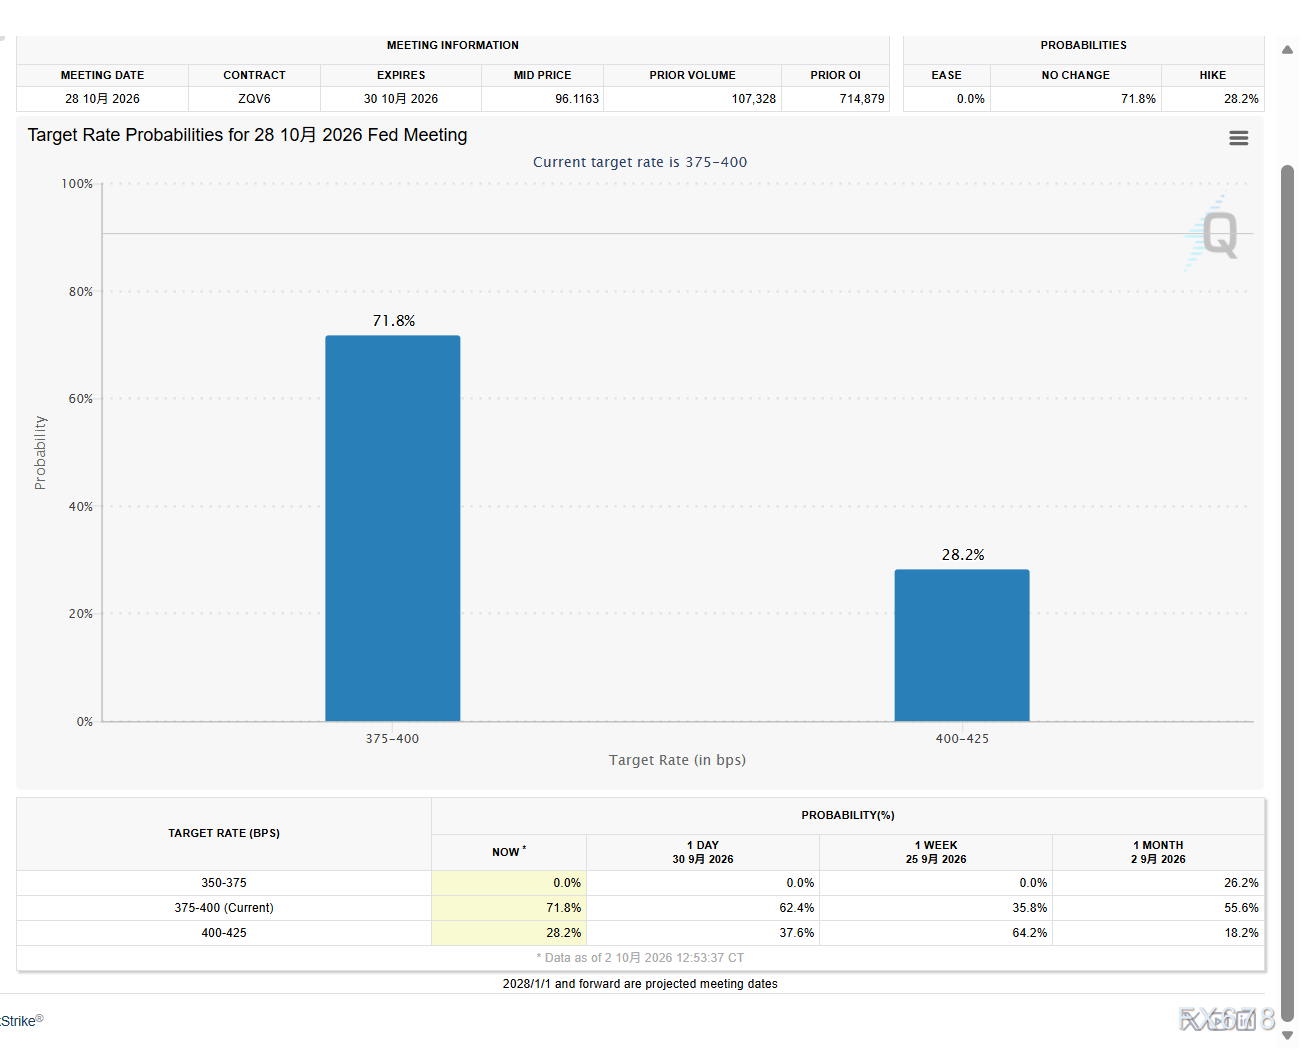
(FedWatch Interest Rate Monitor, Source: CME Group)
Federal Reserve option back in focus: Drawing comparison to the 1990s tech bubble, moderate cooling preferred
Meanwhile, the market has begun trading around the “Fed option.”
The AI boom has pushed up valuations in the US tech sector, leading the market to compare the situation to the technology bubble during the Greenspan era in the 1990s.
Back then, Greenspan did not immediately prick the asset price bubble by forceful rate hikes in response to the boom brought by new technologies, but instead adopted a gradual tightening approach, allowing the bubble to cool naturally and even later cutting rates to support the market.
This expectation continues to alleviate liquidity concerns and further increases demand for gold as a safe-haven asset, thereby supporting gold prices.
ISM Manufacturing PMI reveals structural divergence, exposes the Fed’s internal policy conflicts
At the real economy level, interesting divergence signals have emerged. The September US ISM Manufacturing PMI data can help explain the current conflicts in Fed policy.
The composite PMI edged down to 54.5, below the market expectation of 55.0, leading to an initial reaction interpreting the manufacturing sector as weakening.
However, a breakdown of the data shows the main drag on the composite index stems from a decline in raw material inventories and slight improvement in supplier deliveries, while new orders, order backlogs, manufacturing employment, and input prices all strengthened.
Once inflation falls back and financing pressures ease, against a backdrop of adequate orders, enterprises will have ample potential to replenish inventories and expand hiring.
This set of real economy figures precisely exposes the Federal Reserve’s policy dilemma: on one hand, wanting to control financing costs;
On the other hand, as soon as external risks ease and financing costs drop, the potential for inventory replenishment and enterprise expansion may be released at any time, with aggregate demand rebounding and inflation stickiness being hard to quickly eliminate.
Medium-to-long term: Keep a close watch on the neutral rate, key indicators are nonfarm wage growth and unemployment rate
From a medium and long-term perspective, the market needs to continuously monitor the dynamic changes of the neutral interest rate (r*), which is closely tied to labor market data.
The two main indicators to watch in tonight’s nonfarm payrolls: wage growth rate, and whether the unemployment rate breaks above 4.2%.
The current unemployment rate is stable at 4.1%, near the natural rate widely accepted by the market, suggesting the labor market remains broadly healthy.
If wage growth continues to climb and the unemployment rate stays around 4.1%, market expectations for the neutral rate will rise, which means the Federal Reserve will need to keep rates higher for longer, weighing on gold prices;
Conversely, if the unemployment rate keeps rising and wage growth slows, this would show the labor market is gradually cooling, prompting a lower neutral rate expectation, opening up space for real rates to fall, which will continue to benefit gold.
Conclusion:
The essence of this round's gold price rebound is the market’s struggle with the Federal Reserve’s policy dilemma: AI is causing localized inflation and asset valuation bubbles, while a seemingly marginal slowdown in manufacturing actually hides potential for a demand rebound.
The key factors for gold prices tonight will fall on nonfarm wage data, unemployment rate, and inflation figures.
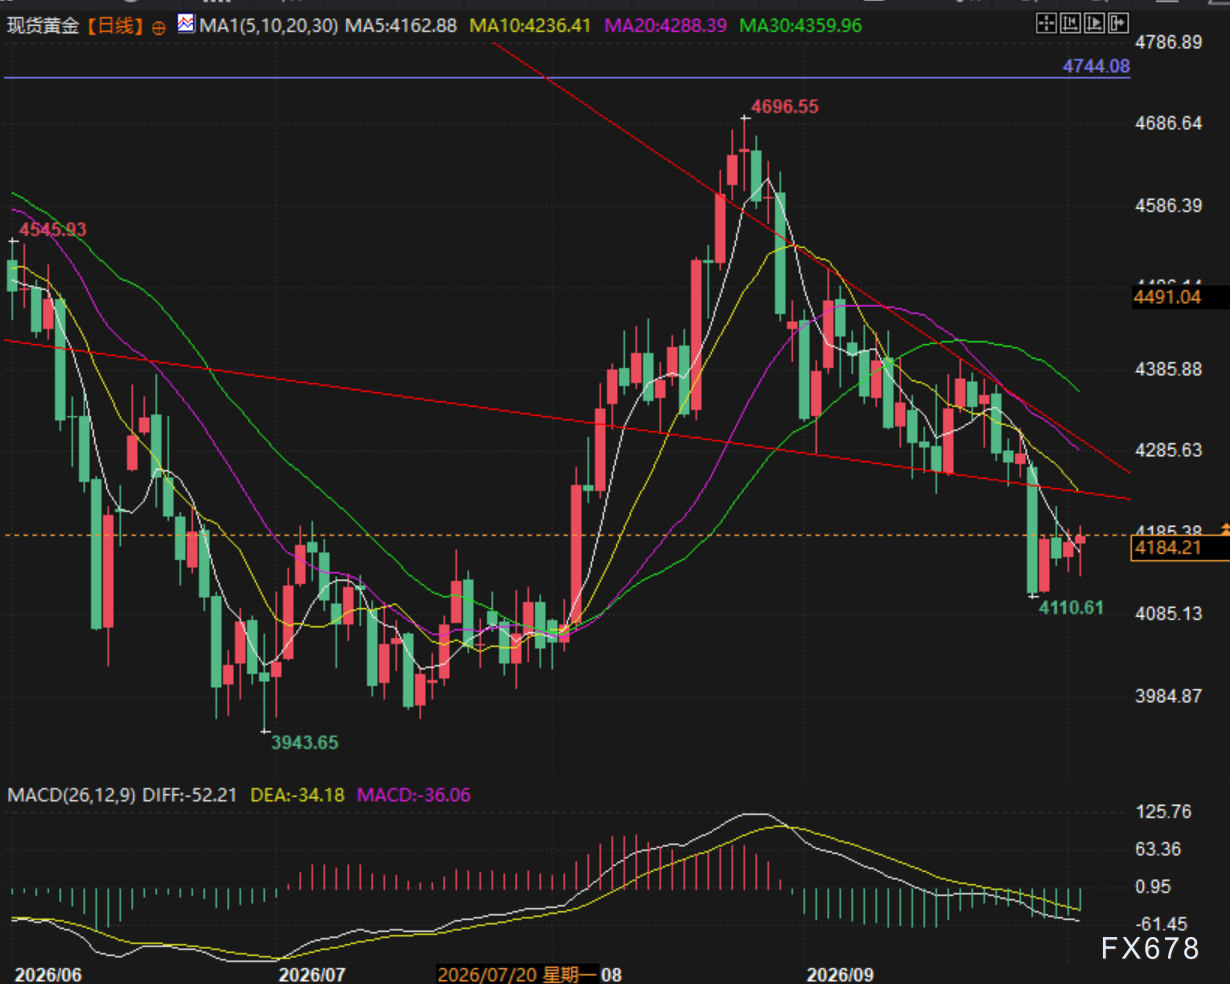
(Spot Gold daily chart, Source: Yihuixun)
At 17:50 GMT+8, spot gold is quoted at $4,183 per ounce.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
GameStop (GME) CEO Ryan Cohen Buys $10 Million of Company Stock
Institutions Declare September Nonfarm Payrolls "Killed" October Rate Hike Expectations! "New Fed News Agency": Jobs Report Does Not Change Fed's Stance, September CPI More Important
"The New Fed's Newsletter" stated that senior Federal Reserve officials have indicated this week that a rate hike in October may not be their baseline forecast. The current report's wage and unemployment rate data do not show the labor market is tightening enough to significantly increase price pressures. Traders’ pricing for an October rate hike dropped from nearly 30% before the data release to about 20%, and at one point, markets even stopped fully pricing in another hike this year. Institutions believe the job market is characterized by “low hiring, low layoffs,” giving the Fed reason to wait for more data; a December rate hike remains possible. Market reaction suggests “bad news is good news,” as Wall Street continues to focus on the 5% US Treasury yield.
Can NEAR crypto rebound? THESE metrics could decide what’s next
SHIB eyes $0.00001217 breakout as RSI signals new upside, could surpass TAO and LTC
Crypto prices
More


