
Wall Street Institutions Warn: The Federal Reserve Has Committed "Original Sin," 10-Year US Treasury Yield May Reach 8%

As the global bond market storm intensifies, Steven Blitz, Chief US Economist at TS Lombard, has issued a warning: The Federal Reserve is repeating the mistakes of history by prematurely easing monetary policy before inflation is fully contained. This "original sin" will drive the yield on 10-year US Treasuries to eventually reach 8% over the coming years.
On Wednesday, the yield on 10-year US Treasuries rose to 5.30%, hitting a new high since 2002, and most Wall Street institutions are debating whether 6% is the next milestone. But in his latest report, "The Original Sin Replayed," Blitz argues this view is "too narrow"—5.75% is only the next interim plateau, and 8% is the long-term target, which will place real pressure on stocks and put an end to the decades-old "buy the dip" mentality among investors.
The core logic behind this assessment is that a combination of loose fiscal and monetary policy will raise the central tendency of inflation and yields in every economic cycle, and the US political environment means this situation will be hard to reverse in the short term. Blitz makes it clear that the political will to truly suppress inflation in the US will not emerge until at least 2029—"but I wouldn’t bet on it," he added.
"Original Sin": Premature Easing, History Repeating
Blitz defines the monetary policy "original sin" as prematurely easing before a downturn has adequately eliminated inflation—"like taking another bite out of the same apple."
In his narrative, this time's "offender" is former Federal Reserve Chair Powell. At the end of last year, facing a cooling job market but rising corporate profits, Powell chose to cut rates—Blitz points out this decision coincided exactly two months before the 2024 presidential election, effectively handing the Biden administration a political gift. Blitz acknowledges Powell faced "enormous pressure" from the government and various contenders for his position, including members of the Federal Open Market Committee (FOMC), who wanted Powell to "close his eyes and ease further."
Now, Trump, Treasury Secretary Bessent, and economic adviser Bessent, among others, want the new Fed Chair Walsh to "turn a blind eye" and pursue easing during the new expansion cycle. At the September policy meeting, Walsh resisted somewhat by raising rates 25 basis points, lifting the federal funds rate to the 3.75%-4.00% range, with a unanimous vote in favor. Blitz’s reaction: "Why not hike by 50 basis points?"
"The Recession That Didn’t Happen": Fiscal Expansion Interrupted the Adjustment
Blitz labels 2025 as "the recession that didn’t happen." After an inverted yield curve lasting around 22 months, private non-farm employment (excluding healthcare) had declined, and real economic growth should have contracted, but this never actually materialized.
The reasons are twofold: first, fiscal expansion was too large; second, the Fed started cutting rates just as corporate profits were recovering. Tariff policy also played a role in amplifying the effect.
Blitz cites two classic Wall Street patterns: First, profits lead employment, and employment leads inflation; Second, the mildest inflation year is usually the first year of recovery. This means 2026 will be a "good year," where, despite shocks from tariffs and oil prices, core inflation will actually ease. But from now, if the stock market continues to cooperate, strong corporate profits will fuel faster hiring, which in turn will push core inflation higher in 2027.
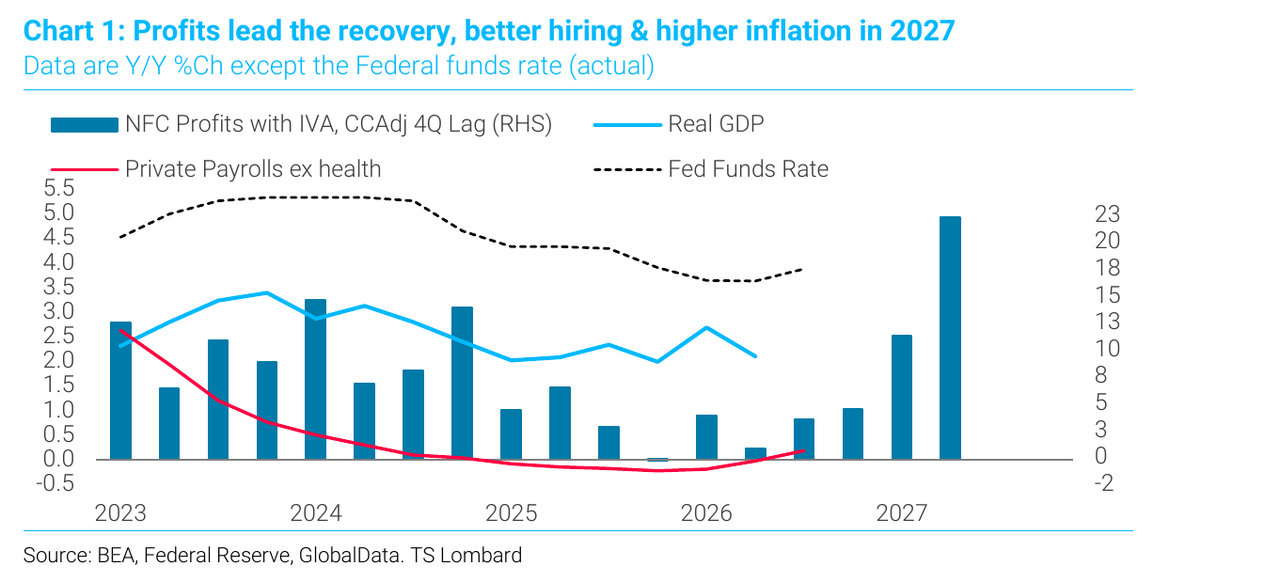
He also points out that the core PCE data for August released this week looked "below expectations" only because the actual figure of 0.247% was rounded down to 0.2%, while a revision to the benchmark artificially suppressed the entire series. Meanwhile, super-core inflation jumped 0.4% month-on-month, "other services" saw the largest rise in history, and education costs hit a record high. The yield on 10-year US Treasuries immediately erased all gains after the PCE data release.
Swap Spreads: The Market Is Pricing Fiscal Risk
The most unique part of Blitz’s analysis is his interpretation of the swap spread. He believes the deeper driver behind rising yields is "excessive sovereign debt supply"—developed market governments must roll over debt, fiscal deficits are expanding faster than nominal GDP, and central banks are no longer acting as marginal buyers.
The most direct signal comes from swap spreads: Investors are increasingly inclined to receive floating overnight secured rates over a 10-year horizon, rather than holding fixed-coupon sovereign bonds. This trend has existed in the US since 2012, but post-COVID it has spread globally—with swap spreads shrinking sharply in the UK and France, and Germany’s situation moving toward balance.
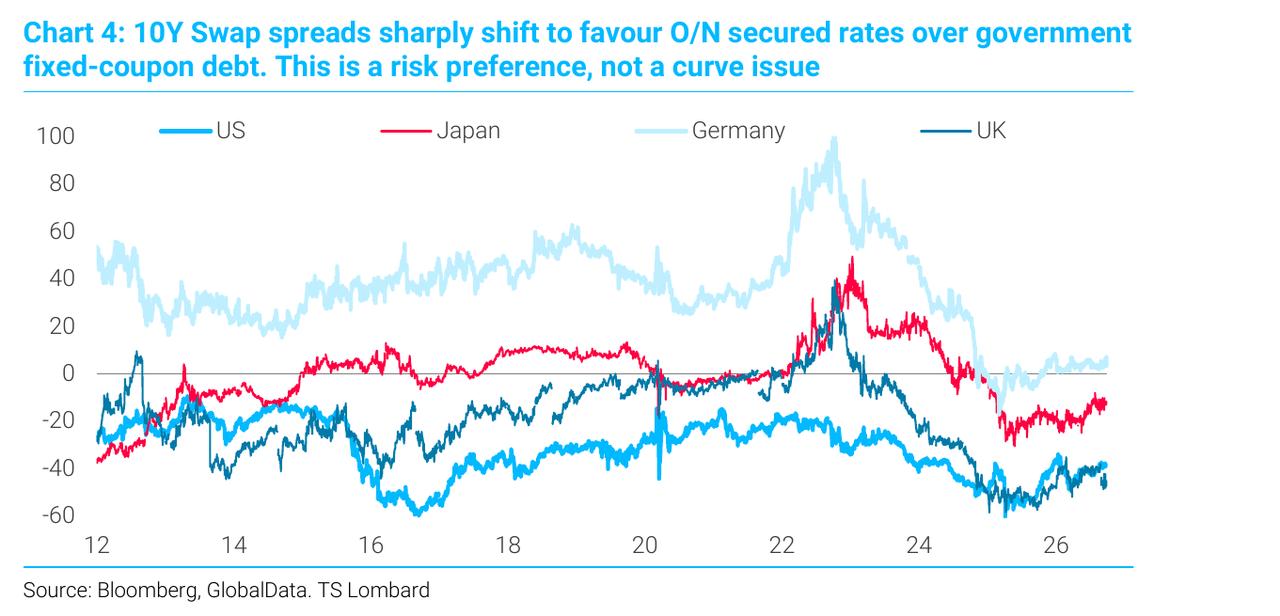
Blitz emphasizes that this is "a matter of risk appetite, not curvature." France and Germany share the same central bank, and the Bank of England typically tracks the ECB, yet swap spread trends in these countries have diverged. What the market is pricing in is fiscal risk, not policy rates or inflation trajectories.
He models the US 10-year swap spread, and finds that even when the effects of curve shape and bank balance sheet regulatory constraints are removed, the market’s preference for US Treasuries continues to dwindle year by year.
Why 8%: Policy Settings and Political Logic
Blitz’s core conclusion is: The combination of loose monetary and expansionary fiscal policy will push up the floor for inflation and yields in every cycle, until the arrival of genuine political will to suppress inflation at the expense of short-term growth.
He sums up this conflict as "Hamilton versus Jackson"—the former stands for running the economy via the central bank, the latter for doing so via government policy. "The populist trend that will choose the next president leans toward Jackson." He encapsulates the past decade of US politics in one sentence: "People are conservative on social issues, liberal on fiscal ones."
The nature of rising yields is equally crucial. Blitz notes that, so far, increases in yields have mainly been driven by real rates, which suppress stocks while sparing the dollar from a sell-off. But if the driver shifts to inflation expectation premia, "stocks can do okay, and dollar bears will finally have their day"—then "the long-anticipated bear market for the dollar will truly begin."
The decisive variable is that net US savings have dropped to zero, with "no sign of improvement." It is against this backdrop that Blitz gives his assessment: "In the end, we will see the 10-year Treasury yield hit 8%."
What Will "Break" First
Blitz doesn’t predict the crash of any specific asset. What he expects to break is a way of thinking—the market’s "firm faith" in inflation returning to 2%, and the reflexive logic that "long stocks and bonds will always pay off." For a generation of investors used to 40 years of falling rates and buying the dip, this will be a major mental adjustment.
Notably, Blitz is not alone. According to reports, Goldman’s delta hedging head Rich Privorostsky said this week that rate moves are "too punitive to ignore," despite the "remarkable resilience" of stocks.
Additionally, the US Treasury is not powerless over yield trends. Rabobank previously called the Treasury’s expanded bond buyback plan in August a "lite version of yield curve control," and warned, "Higher yields worsen fiscal outlooks, pushing up term premiums, which in turn further push up yields"; buyback operations "cut this loop, but may not break it."
Blitz’s view: A government that refuses to accept recession cannot independently choose the upper limit for yields.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Micron's earnings report dazzles, but stock price remains "unmoved"! Wall Street remains optimistic, with the highest target price set at $1,625
Micron's performance and guidance were both strong, but its share price has already surged 237% this year, resulting in a muted pre-market reaction. Wall Street giants such as Deutsche Bank, Bank of America, Goldman Sachs, and JPMorgan remain collectively bullish—26 long-term strategic customer agreements have secured visibility for profits. UBS has even set a top target price of $1,625, strongly affirming Micron's cross-cycle profitability and robust upside potential.
US Stock Market Preview | Three Major Index Futures Rise Together, 10-Year US Treasury Yield Hits Highest Since 2002, Micron (MU.US) Experiences Volatility After Earnings
Before the U.S. stock market opens on Thursday, October 1st, all three major U.S. stock index futures are rising.
Rumor: TSMC (TSM.US) Plans New Texas Campus with Multiple Chip Factories, Total Investment May Reach Tens of Billions of USD
TSMC is considering investing billions of dollars to build more AI chip campuses in Texas.
The Final Meme Season Is Taking Shape: 5 Altcoins Worth Watching Before the Next Big Crypto Move
Crypto prices
More


