
Il discorso falco di Powell colpisce duramente le aspettative di taglio dei tassi, i mercati globali affrontano una “nuova tempesta”!
 Powell, durante un dialogo con i leader aziendali locali ospitato dalla Fed di Dallas, ha affermato: “
① Powell stated in his latest speech that the Federal Reserve is not in a hurry to cut interest rates in a strong economy; ② This hawkish rhetoric quickly stirred up a storm in the global market.
On November 15th, Caixin Media (Editor Xiaoxiang) reported that following the speech by Federal Reserve Chairman Powell in the early hours of Friday Beijing time, Powell stated that the Federal Reserve is not in a hurry to cut interest rates in a strong economy. This hawkish rhetoric quickly stirred up a storm in the global market.
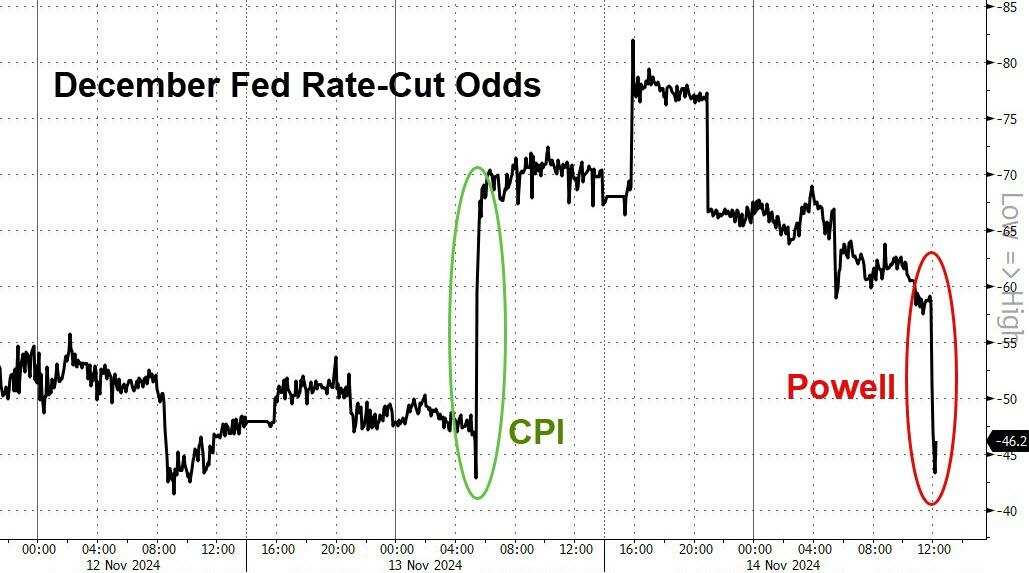
After Powell's speech, the US stock market closed near intraday lows, and the US dollar surged along with US bond yields, with the ICE US Dollar Index hitting a one-year high. Traders reduced the probability of a December rate cut from 80% the previous day to around 50%, sharply contrasting with the CPI release day before.
 During a dialogue with local business leaders hosted by the Dallas Fed, Powell said, "The economy has not shown any signals that require an urgent rate cut. A good economic situation gives us the ability to act prudently when making decisions."
Regarding inflation, Powell pointed out, "The inflation rate is getting closer to our long-term target of 2%, but has not yet been achieved. We are committed to this mission. With the labor market roughly balanced and inflation expectations well anchored, I expect the inflation rate to continue to trend towards the 2% target, albeit with some fluctuations."
To combat inflation, the Fed raised rates to the highest level in 20 years last year and then kept rates at that level for over a year to ensure that price pressures do not return. Since mid-2023, although US inflation has significantly decreased, the slowdown in price growth is sometimes uneven, including in the past two months.
Powell reiterated that the Fed's policy rate path will depend on upcoming data and the evolution of the economic outlook, closely monitoring core indicators of goods and services inflation, excluding housing, which have been declining over the past two years.
The Fed has cut rates in the last two meetings, first making a significant 50 basis point cut in September when there were signs that the labor market might be weakening. At the meeting last week, officials cut the benchmark rate again by 25 basis points to a range of 4.5% - 4.75%.
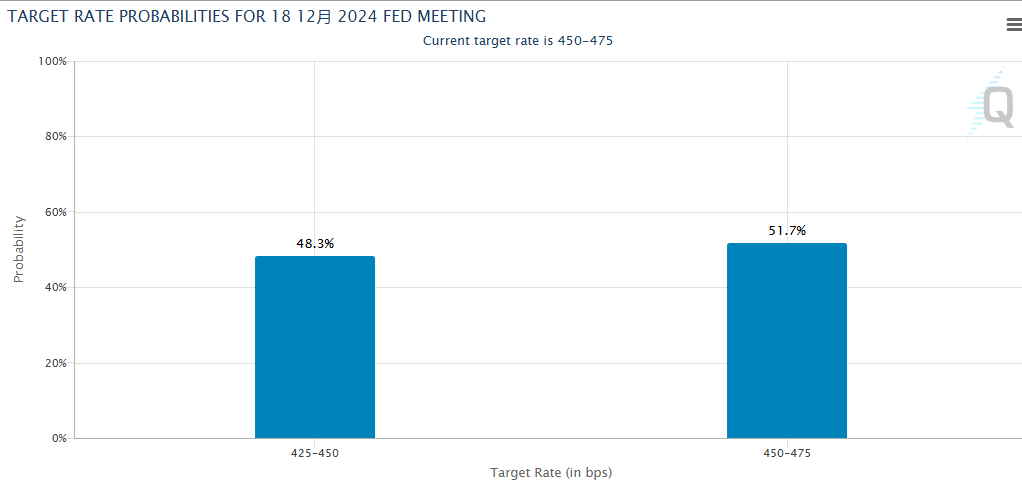
The next meeting of the Federal Reserve will be held on December 17-18. In his latest speech, Powell did not comment on the possibility of a rate cut at the December meeting. However, his remarks clearly dealt a significant blow to the market's expectations for a rate cut next month. The CME FedWatch Tool shows that the likelihood of the Fed achieving a third consecutive rate cut next month has once again become uncertain.
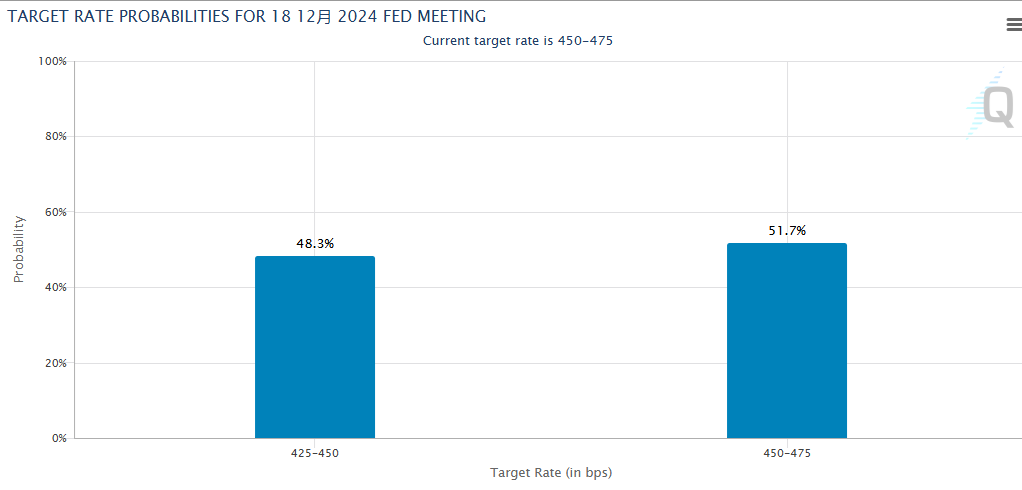
And market traders undoubtedly also quickly reacted to the news.
Global markets face a "new storm".
Most maturities of US Treasury yields rose after Powell's speech overnight, especially short-term yields surged, with the 2-year Treasury yield rebounding 8 basis points to 4.36% at one point.
Major US stock indexes also fell in response. The Dow fell by 0.5%. The S&P 500 index and the Nasdaq both fell by 0.6%, marking the largest single-day decline of the month.
In the forex market, the dollar further strengthened against major currencies on Thursday, with the ICE Dollar Index breaking above the 107 level, reaching a new high in a year, and rising for the fifth consecutive trading day.
Zachary Griffiths, director of credit investments and macro strategy at CreditSights in the US, said, "Powell's speech leans more towards hawkishness, with his future monetary policy bias towards risk management."
"Powell's speech is hawkish," Neil Dutta, Head of Economic Research at Renaissance Macro Research, also pointed out, "I believe they will still cut rates in December because the interest rate policy is still restrictive, and they aim to achieve the neutral rate setting. However, despite this, I think Powell (and the broader consensus) are complacent on the economic front. The downside risks in the short term are greater than people realize."
In fact, even aside from Powell's hawkish speech, a series of recent US economic data does not seem to support a rate cut much. As shown in the chart below, the number of initial jobless claims in the US has now dropped to a six-month low, and inflation data is generally stronger than expected. The economic and inflation situation still seems to face the risk of "not landing".
Market strategist at Murphy & Sylvest, senior wealth advisor Paul Nolte, said that based on the data of the past two days (consumer prices, producer prices, and weekly initial jobless claims), Powell would also find it difficult to become super dovish. All information indicates that job growth remains significant, and inflation continues to exceed the 2% target.
This also raises a question: if the scenario of "Trump comes to power, and Powell suspends rate cuts" really occurs (currently it seems very likely that the Fed will slow down its easing pace early next year), how angry would the "understanding king" who is always unhappy with Powell be?
Michael Feroli, Chief US Economist at JPMorgan, expects that Powell's speech may imply that the Fed will slow down its rate cuts before March next year. He wrote: "We still believe that the FOMC may cut rates in December. But today's speech has opened the door to slowing down the easing pace as early as January next year."
Editor / jayden
Esclusione di responsabilità: il contenuto di questo articolo riflette esclusivamente l’opinione dell’autore e non rappresenta in alcun modo la piattaforma. Questo articolo non deve essere utilizzato come riferimento per prendere decisioni di investimento.
Ti potrebbe interessare anche
La dissoluzione delle “transazioni di consenso” e la nascita di un nuovo consenso! Goldman Sachs spiega: perché le istituzioni stanno attualmente riducendo significativamente le posizioni in AI
Le operazioni "long AI, short tutto il resto", estremamente affollate, stanno subendo una dolorosa decostruzione: il mercato non si accontenta più della "narrazione del bruciare denaro", e i cloud provider di scala ultra-massiccia devono mostrare una reale conversione dei ricavi mentre spendono 1.100 miliardi di dollari in investimenti. Il deficit di energia da 40-50 gigawatt, i costi di capitale in aumento e il cambio del paradigma macroeconomico verso un'epoca di "spese eccessive" stanno trasformando le operazioni AI da questioni di fede a un duro esame di monetizzazione.

La spesa di capitale per l'AI si trova in un dilemma: accelerare mette sotto pressione il flusso di cassa, rallentare compromette la storia di crescita
Nomura Securities ritiene che la narrativa sugli investimenti in AI sia attualmente immersa in una contraddizione interna: se i grandi provider di cloud accelerano la spesa in capitale, il flusso di cassa libero continuerà a essere consumato e la sostenibilità del finanziamento sarà messa in discussione; se rallentano, ciò implica che le aspettative sulla domanda e sulla redditività dell’AI non saranno soddisfatte. Entrambe le strade portano a vendite. Le posizioni long accumulate durante il mercato "agenti intelligenti caldi" di settembre, quando attivate dai catalizzatori negativi, hanno causato massicce liquidazioni e si sono propagate verso i Treasury USA, il mercato valutario e quello delle materie prime, generando un deleveraging sistemico.

Il CEO di Amazon (AMZN.US): La capacità di cloud computing AWS è esaurita fino al 2027, e per il 2028 una grande parte della capacità è già stata prenotata dai clienti.
Venerdì, Jassy ha dichiarato che, con la crescente domanda di infrastrutture per l'intelligenza artificiale (AI), la capacità di cloud computing di Amazon AWS è praticamente esaurita fino al 2027, e per il 2028 una grande quantità di capacità è già stata prenotata dai clienti.

Il crollo del trading AI: Anthropic ritarderà la "super IPO"? La "data prevista per la quotazione" a metà novembre si avvicina.
La finestra temporale è estremamente stretta: secondo le regole della SEC, il file S-1 deve essere presentato al più tardi la prossima settimana e il mercato delle previsioni dà circa l’80% di probabilità di quotazione entro quest’anno. La vendita dei titoli nel settore AI ha gettato ombre sulle prospettive di quotazione, mentre il piano di settembre è già fallito. Diversi operatori di mercato affermano che Anthropic potrebbe subire pressioni per posticipare l’IPO, ma alcuni analisti sottolineano che la forte esigenza di capitale dell’azienda potrebbe spingerla a rispettare i tempi previsti.
Prezzi delle criptovalute
Altro


