
Meta 2026 Q3 Earnings Highlights: Revenue Beats Expectations with 26% Growth to $64.6 Billion, Muse AI Surpasses 10 Million Users, Igniting New AI Growth Narrative
 Bitget2026/10/22 04:58
🔥 US Stock Hotspot Radar is Live! Content: 3 major themes + 6 selected stocks + 7 key events. Where are this week’s opportunities? Click the link to see all 22 trading directions in one chart →
Core View:
Meta’s third-quarter revenue reached $64.6 billion, up 26% year-over-year and ahead of market expectations, driven primarily by strong advertising performance. Impacted by approximately $9.9 billion in legal litigation charges and heavy AI infrastructure spending, the operating margin fell to 20% and free cash flow turned negative. The newly launched personal AI agent Muse quickly exceeded 10 million users in the U.S. and Canada, with shopping scenarios standing out. Management positions it as a long-term higher-ARPU growth engine and announced a new class of non-voting shares to support AI expansion. The stock rose about 2–5% in after-hours trading, as the market focused more on revenue guidance and the Muse narrative than short-term profit pressure.
Detailed Breakdown
1. Overall Revenue and Profit Performance
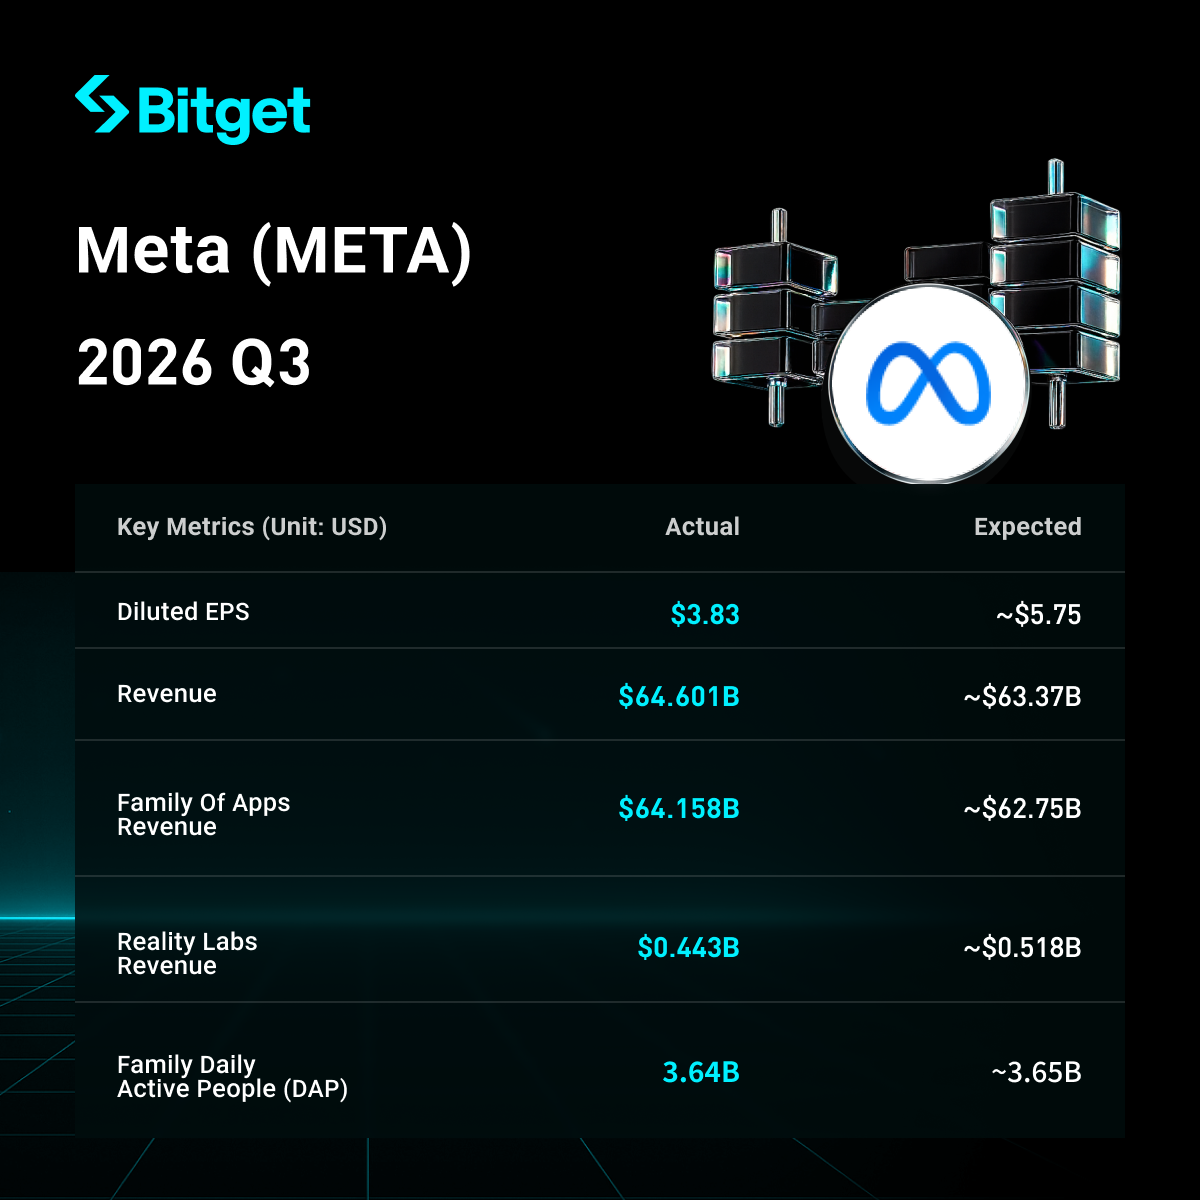
- Quarterly revenue of $64.601 billion, up 26% year-over-year (same on a reported and constant-currency basis), exceeding LSEG and other market expectations of approximately $63.37 billion.
- GAAP diluted earnings per share of $3.83 (including a $9.89 billion charge related to multi-state attorneys general litigation); adjusted diluted EPS of $7.40 excluding the charge and related tax effects.
- Operating income of $12.988 billion, down 37% year-over-year; operating margin of 20% (vs. 40% in the prior-year period). Excluding the legal charge, operating income was approximately $22.88 billion with a margin of about 35%.
- Net income of $9.86 billion, up 264% year-over-year (the prior-year quarter had a low base due to a large tax charge).
- Operating cash flow of $32.786 billion; free cash flow of negative $2.12 billion (vs. positive $10.63 billion in the prior-year period), mainly due to a sharp increase in capital expenditures.
- Ad impressions up 10% year-over-year and average price per ad up 14% year-over-year, reflecting improved ad demand and AI recommendation efficiency.
- Headcount of 66,775, down 15% year-over-year.
2. Muse AI Agent Performance
- Since its launch in early September, more than 10 million users in the U.S. and Canada have set up Muse personal agents (within roughly six weeks), with about 25% of those who set it up using it daily, improving retention.
- Shopping is the most common use case: over 25% of engaged users shop via the AI agent, with average purchase amounts exceeding $200; activity through the Plaid connector exceeded industry expectations.
- Management stated that Muse has achieved product-market fit and is entering a scaling phase, with the goal of serving billions of users; the company is building compute capacity to support more than 1 billion users.
- Currently unprofitable due to “very high compute costs”; cost efficiency is expected to improve more than 10x over the next year, enabling profitability at scale.
- Monetization paths: free for most users, with revenue from transaction fees, subscriptions for advanced models/tokens, enterprise services, and APIs; long-term average revenue per user (ARPU) is expected to exceed that of the existing family of apps (U.S. users currently generate several hundred dollars annually).
- Also launched Muse Wonder (first frontier model) and skill expansions for small businesses (connecting to Shopify, QuickBooks, etc., to assist with ad optimization and operations); planned integration into Meta glasses and privacy features such as confidential VMs.
3. Other Business Segment Performance
- Family of Apps: Revenue of approximately $64.2 billion (including ad revenue of about $63.1 billion, up 26% year-over-year); daily active people (DAP) of 3.64 billion, up 3% year-over-year. AI recommendations improved engagement (e.g., Reels watch time growth), and generative AI ad tools were used by nearly 10 million advertisers.
- Other Revenue: Approximately $1.1 billion, up 59% year-over-year (including WhatsApp paid messaging and subscriptions).
- Reality Labs: Revenue of $443 million, down 6% year-over-year (lower Quest sales partially offset by growth in AI glasses); operating loss of about $4.13 billion in the quarter. Full-year losses are expected at $18–19 billion, narrowing to about $15 billion in 2027, with strategic focus shifting toward AI and glasses.
4. Capital Expenditures and AI Investment Plans
- Third-quarter capital expenditures (including principal payments on finance leases) of $34.9 billion, mainly for servers, data centers, and network infrastructure.
- Full-year capital expenditure guidance narrowed to $135–145 billion (previous lower end was $130 billion).
- Main investment areas: AI compute (to support Muse scaling and core business recommendations) and data center construction; also announced the creation of a new non-voting Class C common stock (effective January 2027, equivalent to a 2-for-1 stock split) to support financing, employee compensation, and acquisitions while maintaining Zuckerberg’s control.
- Management expects AI investments to continue driving strong growth in the core business in 2027 and unlock new revenue opportunities.
5. Next-Quarter Guidance (2026 Q4)
- Revenue guidance of $73–76 billion, with a midpoint of about $74.5 billion, above market expectations of approximately $73.7 billion; assumes an approximately 1% foreign-exchange headwind year-over-year.
- Full-year expense guidance of $175–179 billion (including the legal charge); excluding the Q3 legal charge, full-year operating income is expected to exceed 2025.
- Fourth-quarter tax rate guidance of 15%–17%.
- Reality Labs full-year loss guidance of $18–19 billion, about $15 billion in 2027.
| Revenue | $64.6B (+26%) | $73–76B | - |
| CapEx | $34.9B | - | $135–145B |
| Expenses | $51.6B | - | $175–179B |
| Reality Labs Losses | ~$4.1B | - | $18–19B (2027 ~$15B) |
6. Market Background and Investor Concerns
- Core tension: Advertising business and AI recommendations continue to deliver growth, but AI compute spending has turned free cash flow negative and compressed margins; Muse’s early user and shopping data provide a new narrative, yet compute costs are high and monetization is still early.
- Market challenges: One-time legal charges impact profits; Muse is limited to the U.S. and Canada and requires efficiency gains to scale; Reality Labs continues to lose money, though losses are expected to narrow, it remains a cash drain. Investor focus includes whether Muse’s long-term ARPU can exceed that of existing apps, the feasibility of a 10x improvement in compute efficiency, and the sustainability of growth in 2027.
- Investor reaction: Revenue beat and strong Q4 guidance, combined with Muse highlights, drove the stock up about 2–5% after hours; the market prioritized growth potential over short-term cash flow pressure.
Disclaimer: This content is for reference only and does not constitute any investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
 VIPWeekly Strategy Tesla
VIPWeekly Strategy SpaceX
Abandon 4F², mass production of HBM4, G11 NAND speed up... Micron (MU.US) unveils roadmap at technology seminar, JPMorgan maintains "Overweight" rating
JPMorgan's latest research report points out that Micron Technology detailed its latest technological innovations and long-term plans for its three core product lines—DRAM, HBM, and NAND—at the Investor Technology Webinar held on October 21.

SI business accelerates outbreak and consolidates growth trend! UBS raises target for SpaceX (SPCX.US) to $230
UBS believes that SpaceX continues to meet the market's high expectations for the company, and this trend is expected to continue. UBS gives SpaceX a "Buy" rating with a 12-month price target of $230.


