
Essay: The Next Step in AI Investment—Who Can Turn Computing Power into Profit?

After researching about 3,600 companies, Morgan Stanley has pointed out a noteworthy shift: the investment opportunity in AI is moving from "who is building AI" to "who actually makes effective use of AI."
In recent years, when it comes to AI investment, the first thing the market thought of was chips, servers, and data centers. This is easy to understand: without first building computing power, large-scale application is out of reach.
But as investment continues to grow, one question is becoming increasingly important:Who actually benefits from this spending in terms of revenue and profit? Today I’m sharing this research report with everyone.
In its report released on September 24, "Mapping AI's Rate of Change: From Buildout to Broadening," Morgan Stanley described this stage as moving from "buildout" to "broadening." I believe this is more meaningful than merely discussing whether the "AI rally is over."
First, the chip story isn't over yet
If AI investment is shifting toward applications, does that mean chips and data centers should exit the stage? I don’t think so.
According to the report, demand for AI computing power remains strong, but the construction of data centers is constrained by factors such as power supply, labor, and regulatory approvals. Among these, whether sufficient power can be secured in a timely manner is a key bottleneck.
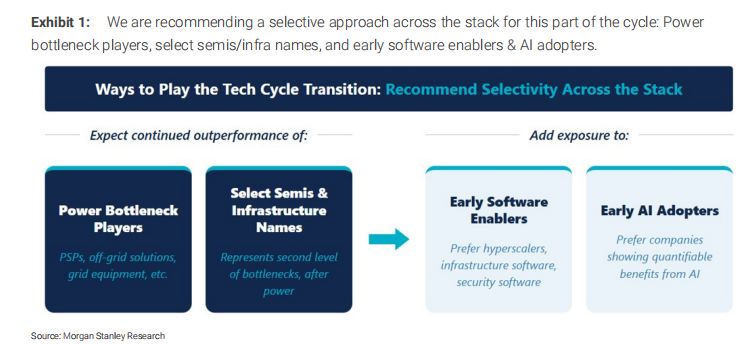
This also explains why Morgan Stanley is still paying attention to some semiconductor companies, data center infrastructure, as well as companies related to power generation equipment, grid equipment, and energy storage.
However, “the whole industry benefits” and “every company is worth buying” are two different things. As the buildout phase progresses, whether orders can be fulfilled, capacity can be delivered, profits can keep up, and how much expectation is already priced into stocks, all become more critical.
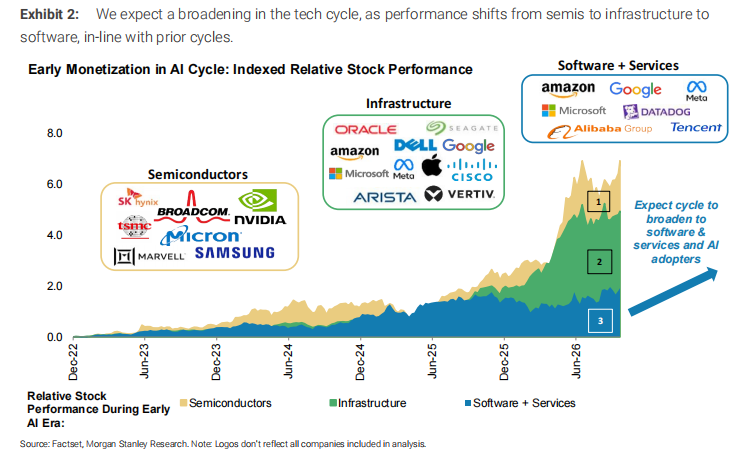
Second, software may begin to receive more attention
Hardware provides the computing power, but software determines whether enterprises can actually utilize the computing power.
When a company wants to integrate AI into its business, it usually needs to organize data first so the AI models can access internal information; afterwards, ongoing monitoring, access, and security management are also required. Only after these foundational steps can AI applications be incorporated into daily workflows.
Therefore, Morgan Stanley believes that foundational software and security software may see demand earlier than many application-specific software solutions. The report highlights related areas such as data platforms, operations monitoring, and cybersecurity; whereas broader application software and service companies might need to wait until clients establish repeatable input-output models.
I think this sequence is important. The market likes to imagine the eventual scale of AI applications, but enterprise spending usually happens step by step.
Third, what truly deserves attention is the profit statement of “AI users”
The most interesting part of the report, for me, is its research on AI users.
So-called "AI users" are not necessarily tech companies. Industries like retail, finance, healthcare, and industrials may all improve customer service, supply chains, R&D, or internal operations via AI. The key is whether these improvements are large enough and can be reflected in financial results.
According to the report, a selected group of AI users have seen consensus earnings-per-share estimates for the next 12 months rise by about 70% over the past two years. This is achange in earnings forecasts, not actual realized profit, and should not be directly interpreted as stock price appreciation.
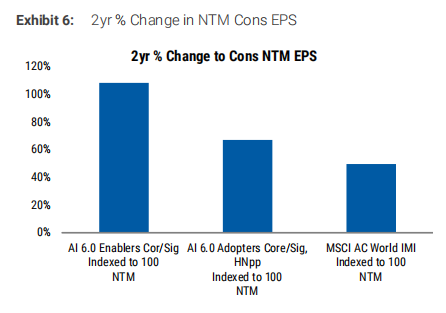
At the same time, the report showed the median forward price-to-earnings ratio for this group was about 18 times, lower than the approximately 22 times for selected AI builders. Morgan Stanley believes that when earnings forecasts improve but valuations do not rise in parallel, AI users merit greater attention.
But I would add a caveat to this conclusion:How much of the profit improvement is truly from AI needs to be verified company by company.A company’s profit margin might also rise due to price increases, cost reduction, or recovery in existing business. If all improvement is attributed to AI, its impact will be easily overestimated.
Some more tangible clues have already emerged. For example, as presented in the report, Airbnb stated that its AI assistant now handles over 40% of relevant customer service requests; Verizon reported over $200 million in energy savings after using AI to optimize networks. These are disclosed cases, indicating that AI is beginning to have measurable business impact, but it's still necessary to observe if results can be sustained and expanded. Another public article by Morgan Stanley also points out that by July 2026, about one-fourth of S&P 500 companies will have mentioned at least one quantifiable AI impact in their earnings or meeting transcripts.
How do I view the next stage?
After reading this report, I won’t draw the conclusion to "sell chips and buy all applications." A more accurate understanding would be:AI investment is evolving from a single main thread into several main threads at different stages of progress.
On one hand are chips and electric infrastructure, still in demand but constrained by supply bottlenecks; on the other are software providers beginning to secure corporate orders; and eventually, those who can turn AI into sustained profit growth.
Going forward, I will pay especially close attention to three issues:
First, when a company claims to use AI, are there concrete business figures to back it up?
Second, can the cost savings or new revenue actually continue flowing to the profit statement?
Third, even if the trend is judged correctly, have current prices already priced in too much optimism?
In the past couple of days, the AI application stocks held by the model have been sold for profit, and ongoing validation is needed going forward.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
$1,999 Foldable iPhone Is Ready, but Apple (AAPL.US) Faces Over $5.7 Billion Patent Penalty
As Apple intensifies its efforts in foldable displays and AI business, it faces a haptic technology patent compensation ruling exceeding $5.7 billion. On September 25, a federal jury in California found that Apple's Taptic Engine, used in certain iPhone and Apple Watch models, infringed on two patents held by Taction Technology.
Prospects for the opening of the Hormuz Strait are overshadowed, Asian bonds under pressure: 2Y Japanese bond yield approaches 2%, 3Y Korean bond yield rises to highest level since 2022
With high oil prices, short-term bond yields in South Korea and Japan have risen.
5% US Treasury pressure weighs on global assets, while Australian government bonds open up a window for allocation? Fixed income giant Pimco calls the rate hike expectations too aggressive
Pacific Investment Management Company (Pimco) holds a constructive view on Australian bonds, believing that market expectations for rate hikes are too high. Pimco stated that the rate hike cycle in Australia has been "fully priced in," and cracks are beginning to appear in the economy, making Australian bonds look attractive, especially in the 5- to 10-year segment of the yield curve.
Only a few stocks are rising! Goldman Sachs warns: US stock market breadth hits the worst level since the 2000 internet bubble, with rare divergence in bond volatility
Flood, a Goldman Sachs partner, believes that leading AI companies are propping up the market indexes, while median stocks have fallen 16% from their highs. More unusually, Garrett, the head of derivatives trading at Goldman Sachs, warns that the bond volatility MOVE index is at an extremely high percentile, yet the VIX remains subdued. Jonathan Krinsky, a strategist at BTIG, points out that while total hedge fund leverage is rising, net leverage is falling, indicating a contradiction of "increasing exposure without increasing direction," and warns: "Something has to give."


